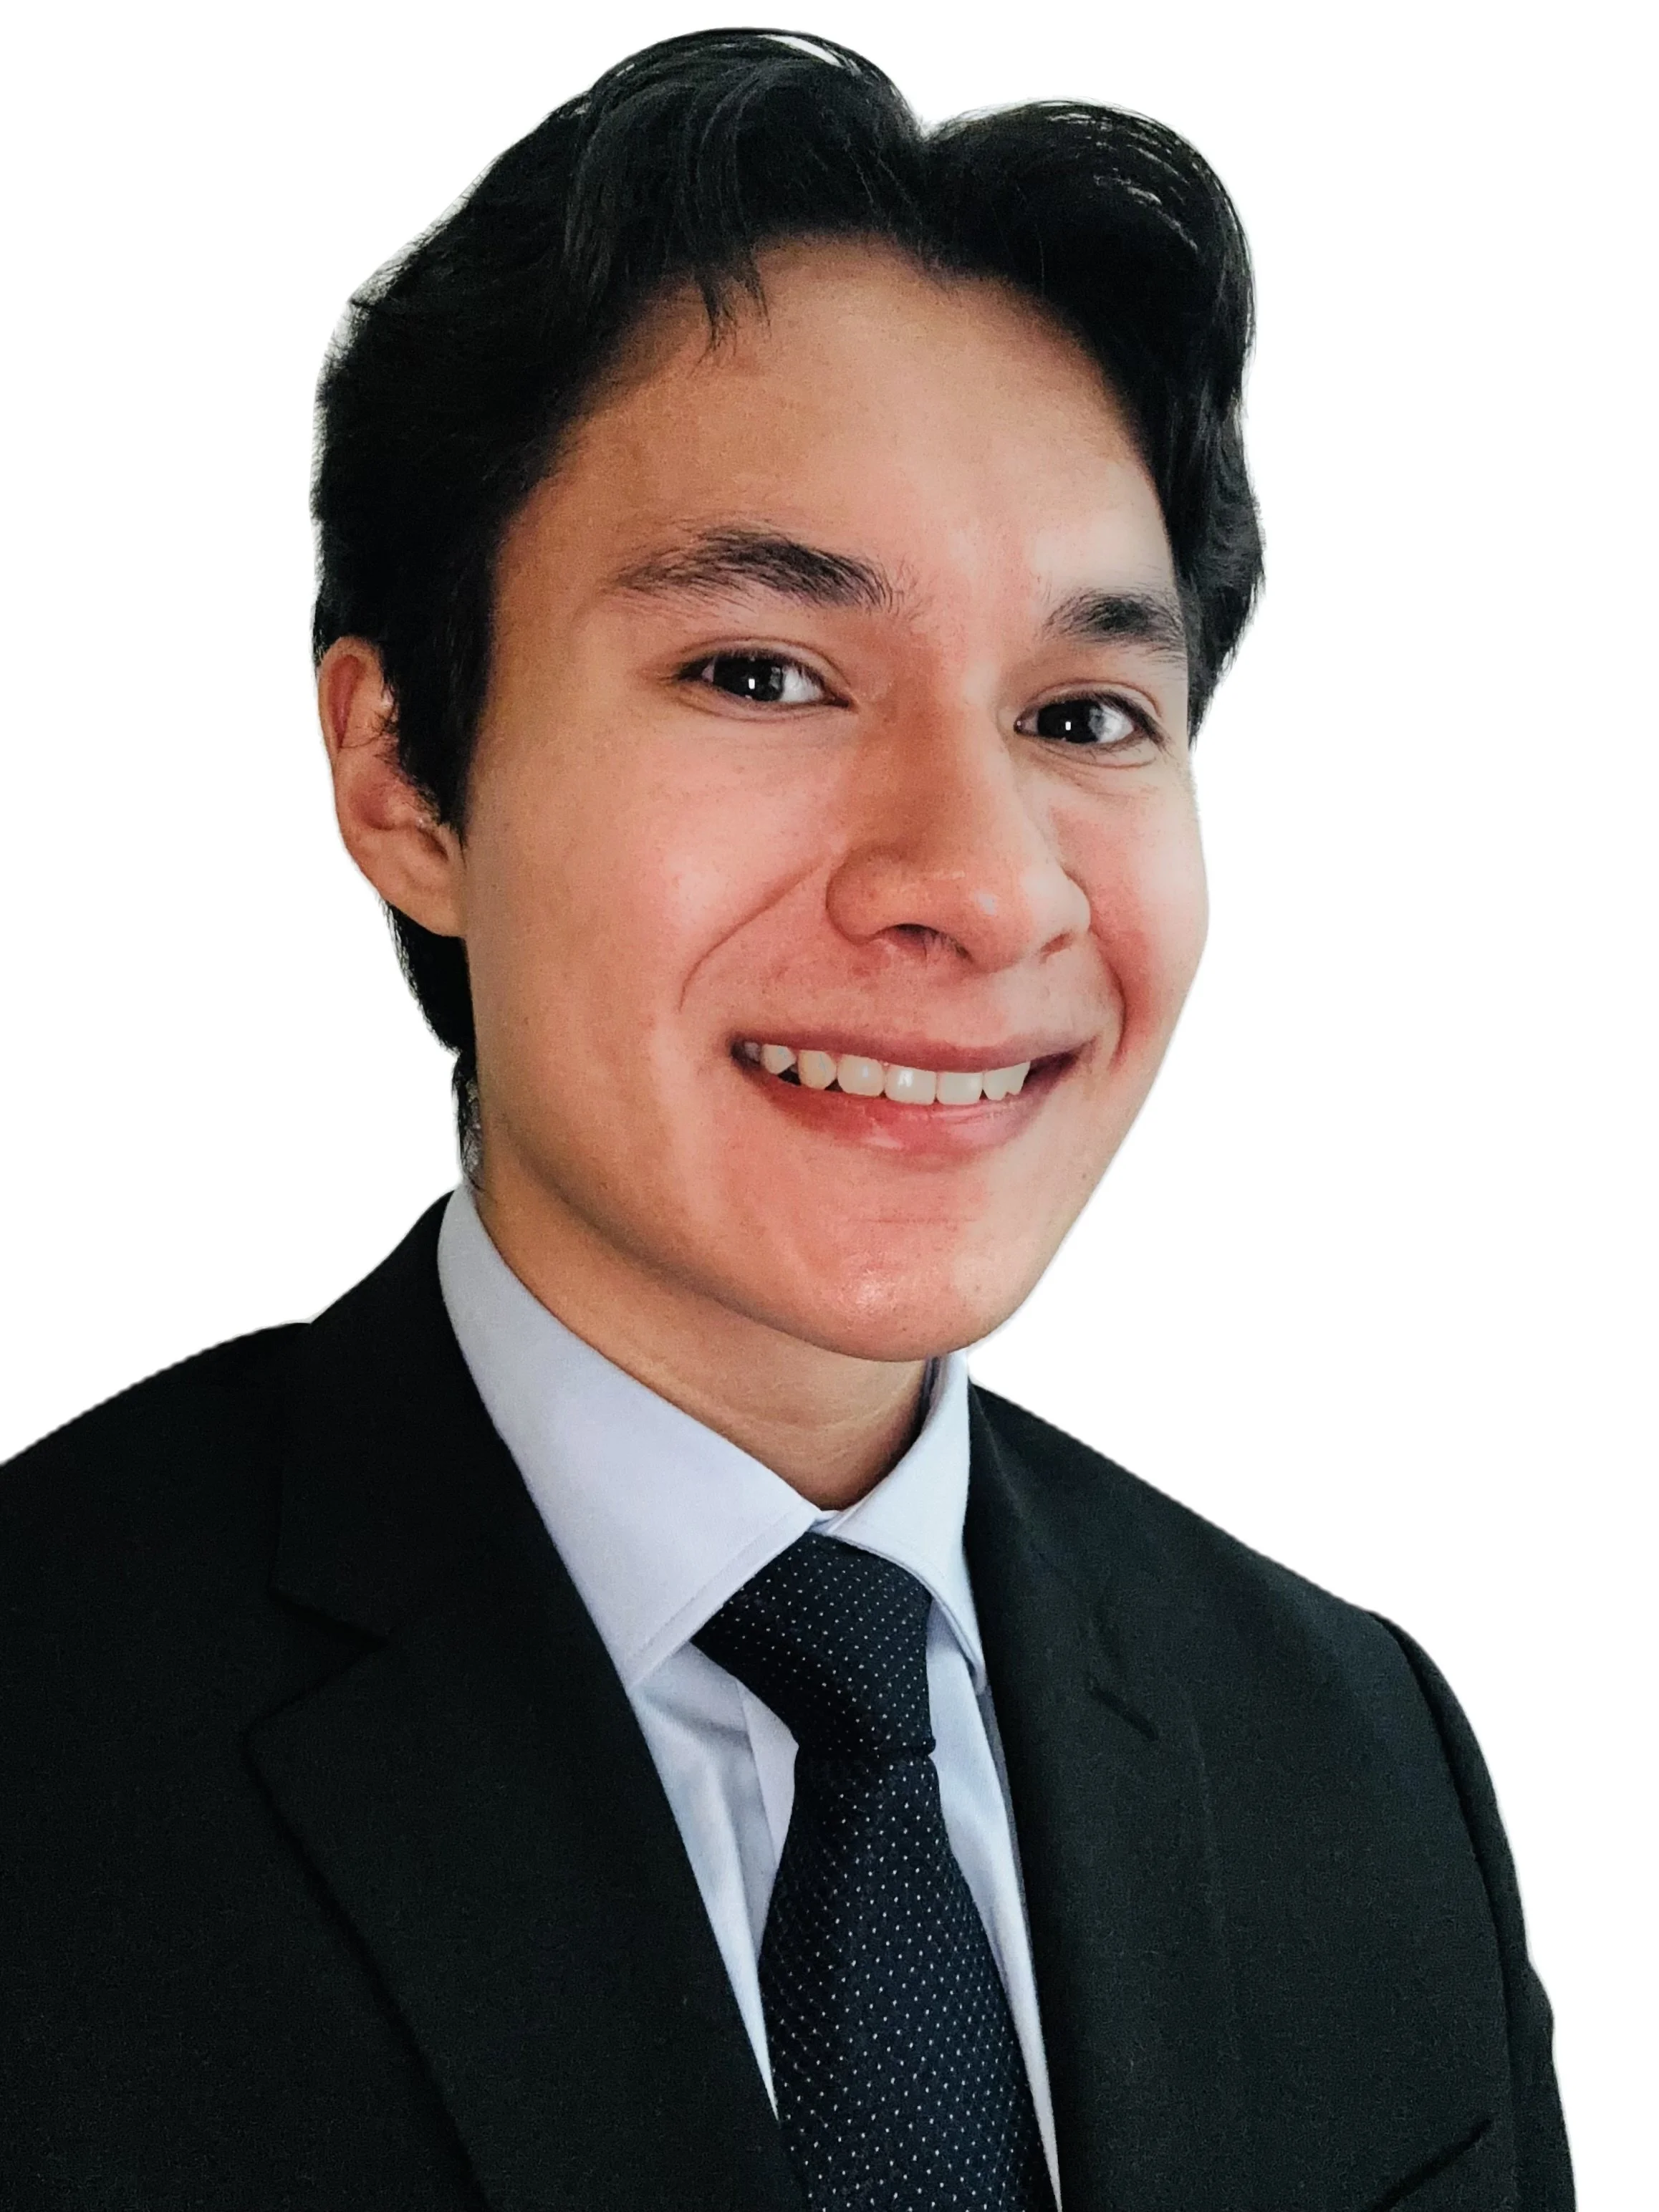
Meet the Founder
I founded Praesidium because equipment finance has a structural conflict of interest most small business owners never see. Most brokers are paid by lenders through backend points embedded in your rate. That isn't inherently bad, as long as the broker tells you. But when compensation is hidden, a broker can place you with whichever lender pays them the largest commission instead of the lender offering you the best terms. That conflict shows up as higher rates, unnecessary fees, and poorly structured agreements that put your business in a precarious position.
Praesidium runs on a different model: you control how I'm paid. Pay me directly, have the lender pay me, or split it. My fee is the same either way, disclosed in writing before any engagement begins, and scales only with deal size, as published below. That removes the financial incentive to steer you toward whichever lender pays the most. There are no upfront charges, retainers, or application fees. I'm paid only when I secure financing you choose to accept.
I’m currently pursuing the CLFP Associate designation from the CLFP Foundation, the equipment finance industry's professional credential, as well as a Bachelor of Science in Finance from Western Governors University. Praesidium is registered as an Illinois Loan Broker in full compliance with the Illinois Loan Brokers Act of 1995. I'm based in the Chicago metropolitan area but I take transactions across the State of Illinois, focusing on equipment financing from $100,000 to $2,000,000 for construction and landscaping contractors. I place transactions with independent finance companies, bank-owned equipment finance divisions, and specialty lenders, matching each deal to the funding source built for it. To see my full fee structure and how I work, continue below.
Christopher Barrientos | Founder & Principal, Praesidium Lending
Praesidium Compensation Model
When you finance equipment through online marketplaces or vendor-referred brokers, referral fees and platform costs are often built into your deal. To cover them, origination fees and rates get marked up, adding thousands of dollars over the life of a loan or lease. And when broker compensation is hidden, brokers can earn more by placing you in financing with higher rates and worse terms, and you'd never know.
My compensation works differently. My fee is published below, and it's the same whether you choose a borrower-paid, lender-paid, or hybrid structure, so I have no reason to steer you toward one over another. It's also the same if a vendor refers you to me: I pay my vendor partners out of my own fee instead of adding their cost to your financing. You see what I earn, in writing, before you sign anything.
I walk through every term of every proposal with you, and I put the conflict of interest that exists in every brokered transaction on the table where you can examine it, instead of burying it in your rate. If you have questions six months or six years after your deal funds, call me. That's the relationship I’m building.
Estimate your financing fee
Transparent pricing that scales with your deal size
Fee rate
3.36%
Estimated fee
$3,360
Estimate only. Final terms depend on deal specific timelines.
See full rate schedule
| Financing amount | Fee rate | Estimated fee |
|---|